
Insurers pay by formula. We help drivers see what the market says
MyFairClaim is a free resource for anyone with a car damage claim. We publish claim guides for all 50 states + D.C. and the major insurers, free tools to check the insurer's number, and reports built from real sales of cars like yours, so you can make your own claim with evidence.
Why we started MyFairClaim
Most drivers find out how car claims work the first time they have one, usually from the insurer that is paying. We think they should hear it from someone else first.
A repaired car is worth less, and you can usually claim it
Once an accident is on its record, a car sells for less even after good repairs. That loss is called diminished value, and in most states the at-fault driver's insurer owes it. Few drivers ask, and many states give you years to file. Diminished value, explained
A total loss offer is a starting point, not a final number
When a car is totaled, the insurer pays what it says the car was worth. That figure often leaves out local prices, sales tax or fees your state's rules call for. You can answer it with evidence. How a total loss is valued
What you'll find here
Most of MyFairClaim is free. You only pay if you want a report to send the insurer.
Claim guides for every state and major insurer
Deadlines, recovery limits and how claims are handled in all 50 states + D.C., plus how State Farm, GEICO, Progressive and other insurers treat these claims.
Browse the state guidesFree tools to check the insurer's number
The diminished value calculator gives you an estimate in about a minute. The total loss page shows how to compare the insurer's offer with local market prices.
Try the free diminished value calculatorReports you send the insurer
A signed report built from real listings near you, with every comparable and the calculation shown. Reports start at $74.99, with no share of your settlement.
Compare plans and pricesSame car, two numbers
Insurers usually start from a formula that caps the loss, then cuts it for damage and mileage. We start from what cars like yours actually sell for nearby.
From our sample report: a 2022 Toyota RAV4 with structural repair near Albany, NY.
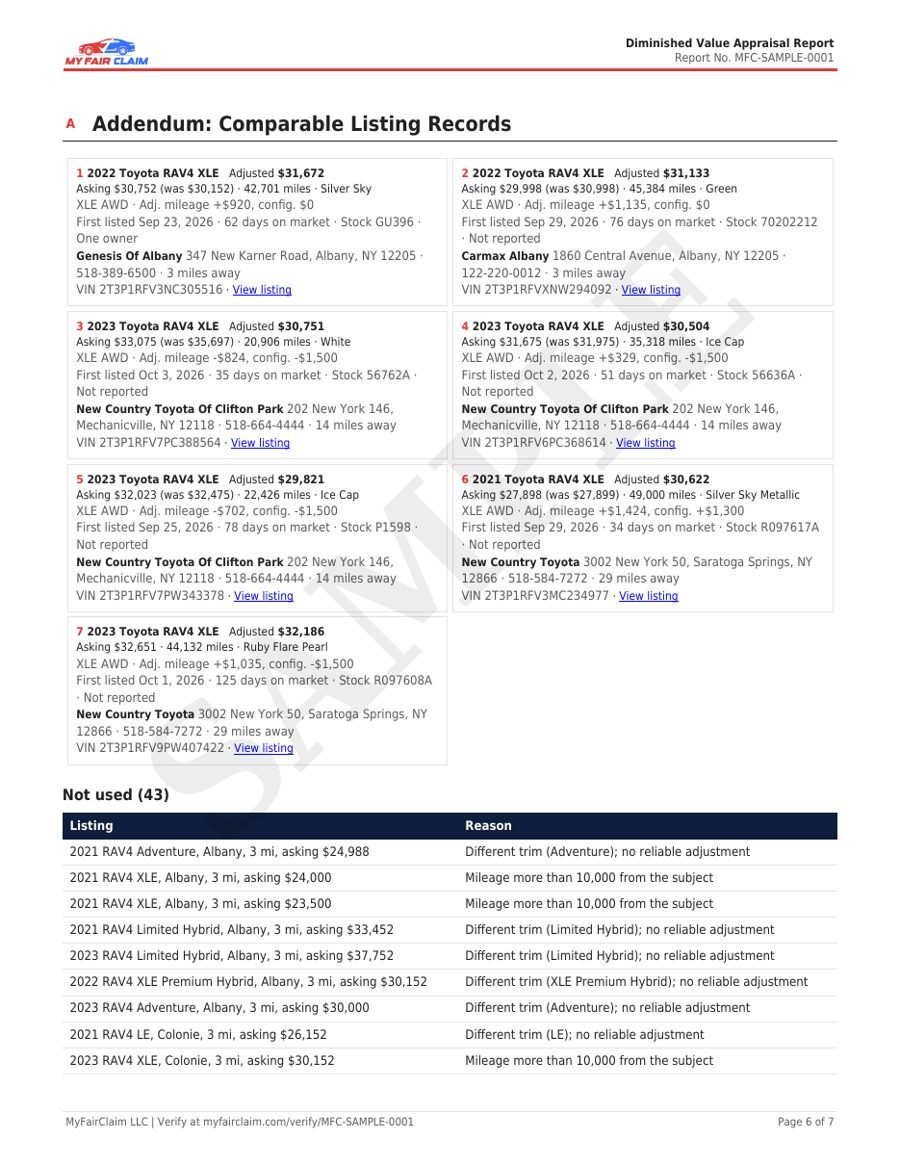
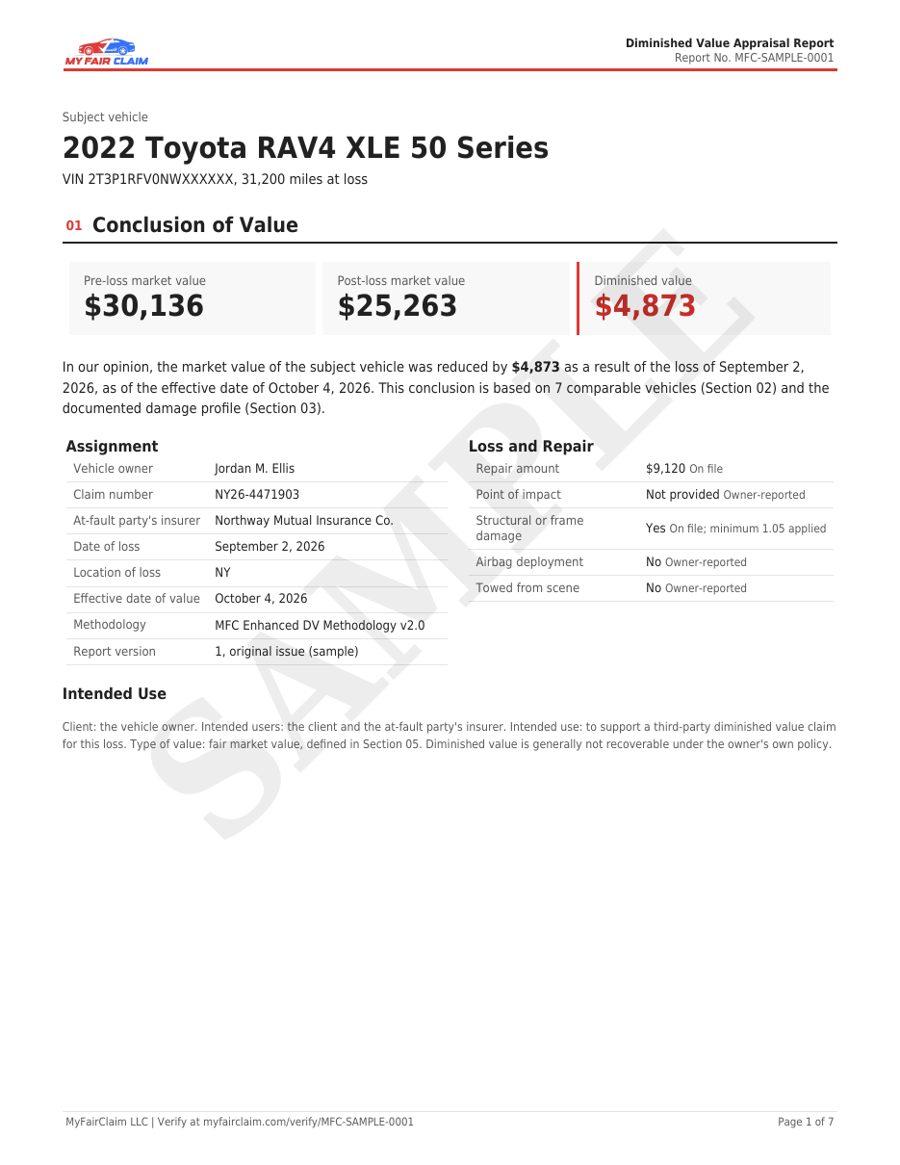
This is what you send the insurer
A signed report with your car's value before and after the accident, every dealer listing we used with its dealer, price and miles, and the calculation step by step. Every report has a number the adjuster can verify on our site.
See a sample reportHow we work
Every report applies the rules and deadlines of the state where you file.
We take no share of your settlement. You pay once and keep what you recover.
The same published method on every report, and a report number the adjuster can verify on our site.
Most reports arrive within seconds. Cars that need hand research usually take a few hours.
How a claim works, and where we help
After an accident, your car is worth less even once it is fixed, because buyers see the accident on its history. That lost value is called diminished value. If the other driver was at fault, their insurance usually has to pay it, but you have to ask, with proof.
You enter the details. We build your report and guides. You send it to the insurer.
- Know your number
Your signed report shows how much value your car lost, from real sales of cars like yours near you.
In every plan - Ask the insurer to pay
You send the at-fault driver's insurer a demand letter with your report attached. The Claim Kit writes the letter and shows who to send it to and how to keep a record.
In the Claim Kit and the Dispute Kit - Push back if needed
Low offer, a formula number, a denial or no answer? The Dispute Kit gives you the replies to send, then walks you through a state complaint or small claims.
In the Dispute Kit, or add it later
Not sure how much help you need? Start with what you need today. If the insurer pushes back, add the next kit from your report page and pay only the difference.
Do you deal with my insurer for me? No. MyFairClaim is self-service: you file your own claim. We don't contact your insurer or negotiate for you, and we take no share of what you recover. That keeps the cost to one flat price, and you stay in control of when to settle and when to push.
Start with the guides
Read before you sign anything. Your state's rules often decide more than the insurer will tell you.
By state
Diminished value, explainedHow a total loss is valuedDiminished value by car modelArticles
You do the filing. We're here when you need us
"Most first offers are formula numbers, and your state's rules decide more than the insurer will tell you. Get the offer on paper and read your state's rules before you sign anything."
Want the full picture first? Read our guide to diminished value, or see how a total loss report works.
Diminished Value Appraisal: Common Questions
Still have questions? Chat with us using the chat box on this page, or email [email protected].